Weekly Insights: Markets Balance Resilient Growth Against Persistent Inflation

Global markets ended the week modestly higher as strong NVIDIA earnings renewed enthusiasm around artificial intelligence, while falling oil prices eased some inflation concerns. These gains were tempered by Federal Reserve Chair Kevin Warsh’s Jackson Hole address, which reaffirmed the Fed’s commitment to its inflation target and kept further tightening on the table.

South African assets also performed relatively well. Gains in financial, industrial and property shares offset weakness in resources, while the rand weakened against the dollar but remained stronger for the year.

US equities advanced, led by technology shares. The Nasdaq gained 0.85%, outperforming the Dow Jones at 0.53% and the S&P 500 at 0.49%. Year to date, the Nasdaq has returned 13.60%, compared with 12.65% for the S&P 500 and 11.44% for the Dow Jones.

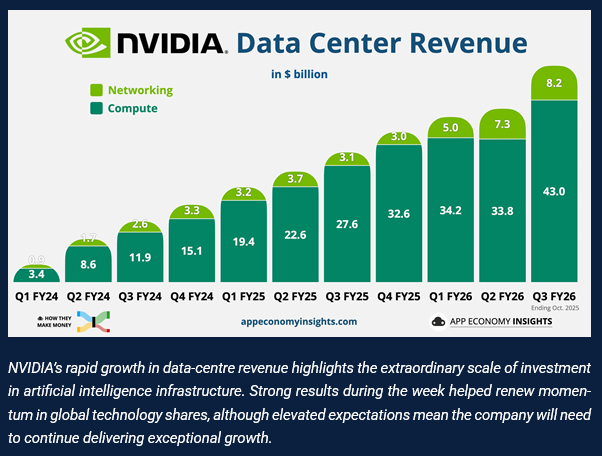
NVIDIA again drove sentiment after reporting strong quarterly results and issuing better-than-expected guidance. Continued investment in artificial intelligence infrastructure supported its shares and the broader technology sector.

The positive corporate backdrop was balanced by a cautious message from the Federal Reserve. Warsh described the economy as resilient, reiterated the Fed’s 2% inflation objective and said further tightening could be required unless inflation moved convincingly towards target. He also advocated less explicit forward guidance to preserve policy flexibility.

Headline PCE inflation rose 3.7% year on year, while core inflation increased 3.3%, in line with expectations. Durable goods orders and employment data remained supportive, although consumer confidence weakened. The US 10-year Treasury yield declined two basis points to 4.72%, even as shorter-dated yields rose following Warsh’s speech, resulting in a flatter yield curve.

European markets delivered modest gains as improving economic sentiment and lower oil prices offset uneven inflation and consumer data. The Euro Stoxx 50 rose 0.36%, taking its year-to-date return to 11.99%, while the FTSE 100 gained 0.07% and is 8.99% higher in 2026.

Eurozone economic sentiment improved for a fourth consecutive month, while Germany’s growth data and business confidence exceeded expectations. This strengthened hopes that Europe’s largest economy may be emerging from its prolonged stagnation.

Conditions were weaker elsewhere. France’s economy stagnated while inflation accelerated, and Spain also reported a sharp rise in headline inflation. In the UK, retail-sector data pointed to continued weakness in consumer demand. The UK 10-year government bond yield was unchanged at 5.07%, while the German 10-year yield rose two basis points to 3.27%.

Asian markets diverged. The Nikkei 225 gained 0.58%, extending its year-to-date return to 31.90%, as lower oil prices and NVIDIA’s results supported Japanese technology and semiconductor shares.

Expectations of further Bank of Japan tightening remained elevated. The Japanese 10-year government bond yield rose five basis points to 2.93%, as inflation data strengthened the case for another rate increase.

Chinese markets were mixed. The Shanghai Composite rose 1.20%, although it remains 0.42% lower for the year, while the Hang Seng declined 1.64% and is down 0.87% year to date. Mainland technology shares benefited from enthusiasm around AI, while Hong Kong was pressured by Alibaba’s large equity placement and concerns about the returns companies may generate from heavy infrastructure spending. Industrial profit data continued to show an uneven recovery, with technology-related industries outperforming sectors more exposed to domestic demand.

Market Moves of the Week:
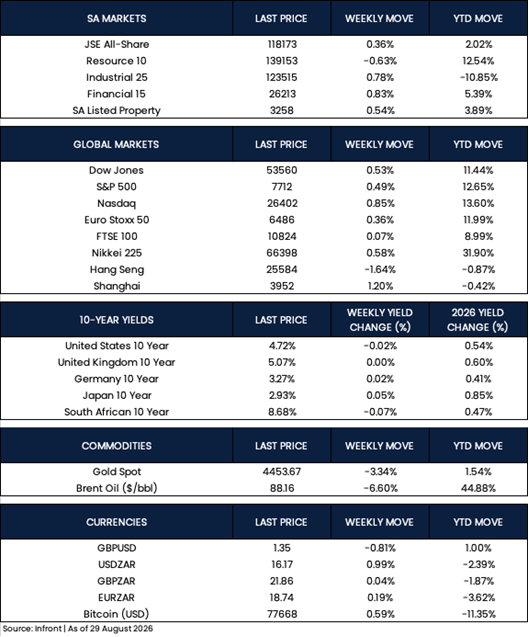
South African equities advanced, with the JSE All-Share Index rising 0.36% and moving 2.02% higher year to date.

The Financial 15 gained 0.83%, the Industrial 25 rose 0.78%, and listed property added 0.54%. Resources underperformed, with the Resource 10 declining 0.63%, although it remains the strongest domestic sector this year with a gain of 12.54%.

Commodity prices weakened. Gold fell 3.34% to approximately $4,454 per ounce, while Brent crude declined 6.60% to $88.16 per barrel. Despite the weekly fall, Brent remains 44.88% higher in 2026, keeping energy prices an important inflation risk.

The rand weakened over the week, with the US dollar rising 0.99% to R16.17. Nevertheless, the rand remains approximately 2.39% stronger against the dollar year to date. The pound fell 0.81% against the dollar, while the euro gained 0.19% against the rand.

Domestic bonds performed well, with the South African 10-year government bond yield declining seven basis points to 8.68%. Investors remained focused on National Treasury’s July budget figures for further indications of the country’s fiscal position.

Chart of the Week:
As always, we appreciate your support and value your trust in LNKD Investment Managers.

The information included above as well as individual companies and/or securities mentioned should not be construed as investment advice, a recommendation to buy or sell or an indication of trading intent on behalf of any LNKD Investment Managers product. This material is provided for informational purposes only and is not intended to be investment advice or a recommendation to take any particular investment action. Information contained herein is based upon sources we consider to be reliable; we do not, however, guarantee its accuracy. All charts and tables are shown for illustrative purposes only.

LNKD Investment Managers is an authorised financial services provider (FSP 51257).

Weekly Insights: Dollar Slides to Three-Month Low on Treasury Buyback Surprise

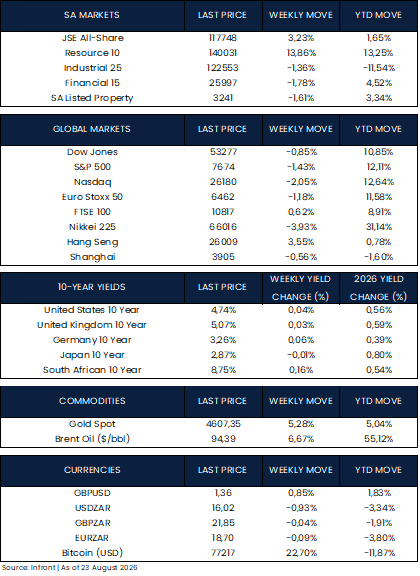
US equities closed the week on a firmer note, with Friday’s session pausing a run of losses after data showed business activity expanding at its fastest pace in more than four years. The S&P 500 added 0.4%, the Nasdaq 100 rose 0.3%, and the Dow gained 518 points on the day. That relief came too late to rescue the week, however, as elevated Treasury yields, renewed US-Iran tensions, higher oil prices and weakness in semiconductor and AI-related names weighed broadly on sentiment. Mixed retail earnings added to the cautious tone. Over the week the Nasdaq Composite shed 2.05% and the S&P 500 lost 1.43%, while the Dow held up comparatively well, down 0.85%.

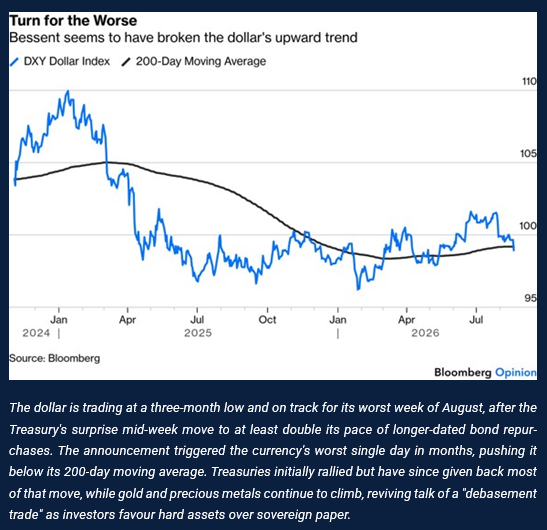
Fixed income remained the dominant story. Long-term Treasury yields pushed higher early in the week, with the 30-year touching its highest level since 2007, as investors grappled with a deteriorating US fiscal outlook and heavy government and corporate issuance. Rising oil prices on the back of renewed US-Iran tensions added a further inflationary layer. The Treasury’s mid-week announcement that it would at least double the size of its planned long-term debt buybacks sparked a rally that pulled 30-year yields down by roughly 8 basis points and weighed on the dollar, but much of that move unwound later in the week as investors questioned whether the buyback programme goes far enough to offset the structural pressures on long-dated bonds.

Minutes from the Fed’s July meeting showed participants generally expecting inflation to moderate through the remainder of the year, though they flagged that the outlook remains highly uncertain with risks skewed to the upside, and that further policy tightening would likely be needed should inflation fail to decline.

On trade, the US imposed 50% tariffs on a tranche of Canadian goods just after midnight on Saturday, after the two countries failed to reach a deal. The measures cover around $20 billion of exports, including niche categories such as wooden ice hockey sticks which represents just over 5% of Canada’s exports to the US, and are unlikely to prove a material economic shock to either side.

European markets were not spared the global bond sell-off, with the STOXX Europe 50 down 1.18% for the week as investors weighed inflationary pressure and uncertainty over a lasting US-Iran peace deal. The UK’s FTSE 100 bucked the trend, climbing 0.62%, even as labour market data disappointed: payrolled employment fell 13,000 in July, a sixth straight monthly decline, while unemployment held at 4.9%, slightly above the 4.8% expected.

Japan saw the sharpest regional drawdown, with the Nikkei 225 falling 3.93% as renewed Middle East risk, higher oil prices and rising yields drove a broad risk-off move, hitting technology and semiconductor names particularly hard. The yen stayed historically weak around JPY 159 to the dollar. Second-quarter GDP growth disappointed at an annualised 1.1%, well short of the 2.0% consensus and down from a revised 1.9% in Q1, with weak capital expenditure and softer consumer spending offsetting resilient exports. Inflation data added to the case for a near-term Bank of Japan hike, with core CPI up 1.8% year-on-year in July, in line with expectations and up from 1.6% in June.

Chinese equities were mixed, with Hong Kong outperforming the mainland. July activity data showed a broad-based slowdown: industrial output grew 4.5% year-on-year, down from 5.3% in June and below expectations despite continued strength in high-tech production, while retail sales growth slowed to 0.6% from 1%, underscoring persistently soft domestic demand. The Shanghai Composite ended the week 0.56% lower in local currency terms.

In commodities, Brent crude held little changed near $94 a barrel on Friday as markets weighed signs that Iran may be seeking a resolution to the conflict, even as this followed a more than 6% rise in oil prices for a second consecutive week. Iranian President Masoud Pezeshkian signalled a preference for ending the war from a position of strength, framing the existing memorandum with Washington as an Iranian win, comments that offered some relief after US Treasury Secretary Scott Bessent warned of the toughest sanctions yet on Tehran. Gold extended its rally to around 5% for the week, climbing above $4,600 an ounce, its highest level since mid-May, supported by renewed concern over US fiscal sustainability following the Treasury’s expanded long-dated debt purchases, which pushed both yields and the dollar lower.

In the week ahead, interest rate and the sovereign yield outlook will remain front and centre as markets weigh elevated energy prices, widening deficits and heavy corporate credit issuance. The Fed’s Jackson Hole Symposium will be the focal point, with FOMC speeches likely to set the tone on the path for monetary policy and balance sheet duration. Elsewhere, the ECB releases its meeting accounts, Germany publishes consumer and business confidence data, and Spain and France report CPI prints, while Japan releases consumer confidence and unemployment data.

Market Moves of the Week:

South African inflation surprised to the downside, easing to 4.3% year-on-year in July from 5.0% in June and below the 4.5% consensus in a Reuters poll. Statistics South Africa attributed the slowdown to softer food inflation, smaller municipal tariff increases and a sharp pullback in fuel costs, with food and non-alcoholic beverage inflation falling to its lowest level in more than 16 years at 0.9%, driven by cereals and meat, while petrol and diesel prices fell 7.1% and 11.7% respectively between June and July. The reading, still comfortably above the SARB’s 3% target, reinforces the case for the central bank to hold rates steady at its next MPC on 23 September, having already surprised the market by keeping rates unchanged in July on the view that policy is sufficiently restrictive to return inflation to target within two years. That said, analysts caution the relief may be short-lived, with renewed US-Iran hostilities having since pushed global oil prices back up; forward rate agreements are currently pricing a 70% probability of a 25 basis point hike at the September meeting rather than a cut.

Local markets had a strong week. The rand firmed through R16.00 to the dollar for the first time since February, trading at R15.99 intraday on Friday, its best level since before the outbreak of the Iran conflict, supported by a weaker dollar following the US Treasury’s expanded long-bond buyback programme, rising gold prices, an improving domestic fiscal backdrop and the currency’s continued appeal in the dollar-funded carry trade given low volatility.

The JSE All Share Index rallied over 3% for the week led by a strong showing from resource counters and precious metals miners in particular as gold extended its rally to a third consecutive weekly gain.

Chart of the Week:

The information included above as well as individual companies and/or securities mentioned should not be construed as investment advice, a recommendation to buy or sell or an indication of trading intent on behalf of any LNKD Investment Managers product. This material is provided for informational purposes only and is not intended to be investment advice or a recommendation to take any particular investment action. Information contained herein is based upon sources we consider to be reliable; we do not, however, guarantee its accuracy. All charts and tables are shown for illustrative purposes only.

LNKD Investment Managers is an authorised financial services provider (FSP 51257).
Weekly Insights: Mixed Markets as Inflation Cools

After several data-heavy weeks, markets entered a quieter period, with investor sentiment remaining constructive and volatility falling back towards its 2026 lows despite ongoing geopolitical uncertainty in the Middle East. Inflation remained the key focus, with signs of renewed moderation helping to ease concerns around persistent price pressures and supporting fresh highs in parts of the US equity market. With the Federal Reserve’s next policy meeting only in September, attention now shifts to incoming labour market and inflation data.

US equities ended the week mixed as softer inflation and positive AI-related earnings were balanced against higher oil prices, uncertainty around the Strait of Hormuz and weaker consumer data. Smaller companies outperformed, while the S&P 500 posted a modest gain and the Dow Jones declined. Headline inflation rose 3.4% year on year in July, while core inflation eased to 2.5%, with producer prices also coming in softer than expected. This reduced expectations of another Fed rate increase in September, although policymakers continued to caution that inflation risks remain.

Consumer data was less supportive, with retail sales falling 0.6% in July and consumer sentiment weakening in August. While this points to some moderation in household demand, steady economic growth and supportive earnings expectations continue to underpin markets. Investors will be watching closely to see whether inflation can continue to ease while the US economy maintains its momentum.

European markets were mixed as higher energy prices and shifting sector leadership influenced sentiment. Rising gas and fuel costs added pressure to industrial activity, while extreme heat disrupted French nuclear generation and low water levels on the Rhine affected German logistics. Despite these challenges, eurozone investor confidence returned to positive territory in August. In the UK, second-quarter GDP grew by 0.4%, although industrial activity remained subdued, while persistent inflation concerns kept government bond yields elevated.

Looking ahead, UK labour market and inflation data will be important for the Bank of England. Wage growth is expected to moderate further, but higher energy costs could push headline inflation back towards 2.9%, reinforcing the case for a cautious approach to monetary policy.

Japan was the standout major equity market, with the Nikkei 225 gaining 4.74% and the TOPIX rising 3.00%. Strong technology earnings, semiconductor demand and a weaker yen supported equities, although persistent inflation and currency weakness increased speculation that the Bank of Japan could raise rates again. Producer inflation remained elevated at 7.2% year on year, while the 10-year government bond yield rose to 2.87%.

Chinese markets lost momentum as the week progressed, with the Hang Seng declining 2.15% amid weakness in large technology shares and mixed earnings. Inflationary pressures continued to ease, with consumer inflation slowing to 0.5% and producer inflation to 3.5%. Policy support remained focused on the property sector, with Beijing relaxing homebuying restrictions, while Hong Kong announced plans to broaden the Hang Seng Tech Index to include more AI and robotics companies.

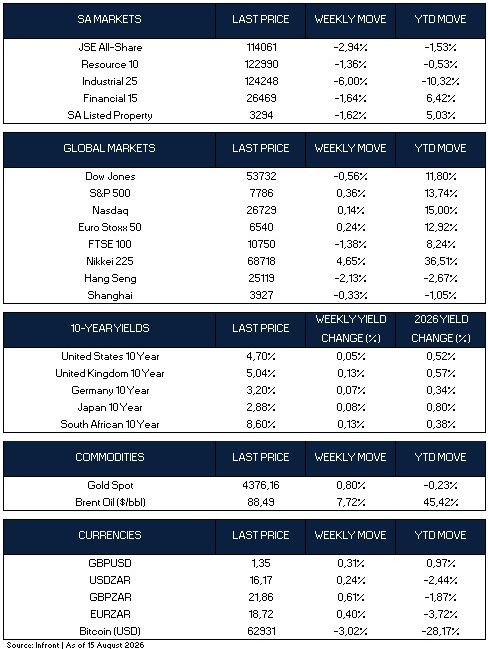
Overall, global markets delivered a mixed performance. The S&P 500 and Nasdaq gained 0.36% and 0.14% respectively, while the Dow Jones fell 0.56%. The Euro Stoxx 50 rose 0.24% and the FTSE 100 declined 1.38%, while Japan significantly outperformed other Asian markets. Government bond yields moved higher across major developed markets. Brent crude oil gained 7.72% for the week and is now 45.42% higher year to date, while gold rose 0.80%. Bitcoin declined 3.02% and remains 28.17% lower in 2026.

Market Moves of the Week:

Turning to South Africa, the labour market weakened in the second quarter, with the official unemployment rate rising to 33.6% from 32.7%, while the number of unemployed people increased to 8.5 million. Employment declined across seven of the ten sectors tracked, highlighting continued pressure on households and the broader economy.

There were, however, some tentative signs of improvement in industrial activity. Manufacturing production increased 0.9% month on month in June, while mining output rose 0.3%. On an annual basis, both sectors remained in contraction, although the pace of decline moderated, with manufacturing down 1.7% and mining down 4.0%.

Elsewhere, the Constitutional Court blocked Shell-led offshore exploration along the Wild Coast, overturning an earlier ruling that had allowed the project to proceed. The decision follows years of legal challenges and again highlights the importance of regulatory certainty and policy execution in attracting long-term investment into South Africa’s energy sector.

Against this backdrop, South African markets had a difficult week. The JSE All Share Index fell by 2.94%, led by a 6.00% decline in industrial shares, taking the sector’s year-to-date loss to 10.32%. Financials and resources also moved lower, declining by 1.64% and 1.36% respectively, while listed property fell by 1.62%. The rand weakened slightly against major currencies, with the US dollar closing the week at R16.17, while the South African 10-year government bond yield increased to 8.60%.

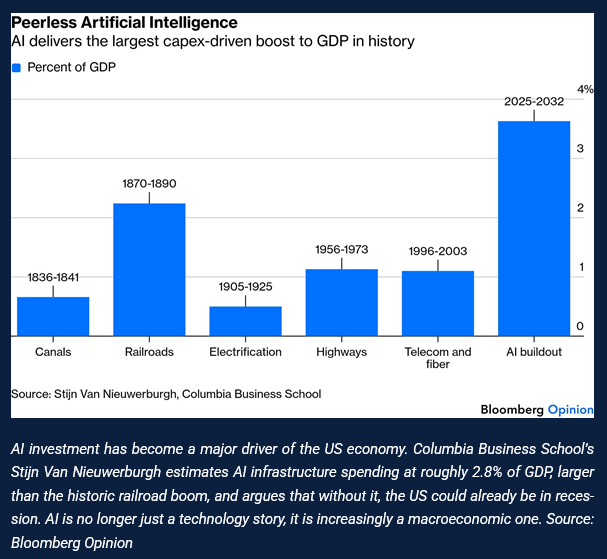
Chart of the Week:

As always, we appreciate your support and value your trust in LNKD Investment Managers.

Important Information

The information included above as well as individual companies and/or securities mentioned should not be construed as investment advice, a recommendation to buy or sell or an indication of trading intent on behalf of any LNKD Investment Managers product. This material is provided for informational purposes only and is not intended to be investment advice or a recommendation to take any particular investment action. Information contained herein is based upon sources we consider to be reliable; we do not, however, guarantee its accuracy. All charts and tables are shown for illustrative purposes only.

LNKD Investment Managers is an authorised financial services provider (FSP 51257).
Weekly Insights: Markets rally as soft jobs data cools rate hike fears

Global equities extended their advance this week, with the S&P 500 up 3.6% and the Nasdaq surging 5.2% on a chip stock rebound, both indices posting their best weekly performance since April. The catalyst was a surprisingly weak July US jobs report: nonfarm payrolls fell by 23,000 against expectations of an 83,000 gain, while unemployment ticked down to 4.1% as participation dropped to a five-year low. Markets read the print as a green light for the Fed to stay on hold, with futures now pricing a clear majority for no move at the September meeting, a sharp reversal from the 55% hike probability priced just a day earlier. The 10-year Treasury yield fell nine basis points to 4.65% on the back of it.

Beneath the headline numbers, US small-cap earnings are quietly having their best season since 2001, with Russell 2000 sales growth running at 9%, up from 7.5% pre-season and broadening out from energy, materials and industrials rather than staying concentrated in mega-cap tech.

In Europe, the STOXX 50 added 2.6% on firmer risk appetite, even as the geopolitical backdrop stayed unsettled. Services PMIs in France and Germany improved meaningfully with France gaining to 49.8 from 46.8, its best reading in seven months, while Germany increased to 49.8 from 48.6, though both remain in contraction territory below 50.

A less-discussed but increasingly relevant theme is water: record-low levels on the Rhine and Danube are pushing up barge freight costs and forcing production cuts at Hungarian auto and battery plants, with knock-on pressure on Romanian power generation.

The UK saw services and broader private-sector headcount contract for a 22nd straight month, matching the length of the 2008–09 downturn, while government reluctance to rule out higher bank taxes in the upcoming budget is adding a layer of uncertainty for financials. The FTSE 100 still managed a 0.3% gain for the week.

In Asia, the yen firmed early in the week on intervention speculation before the persistent US-Japan rate differential reasserted itself. The Bank of Japan remains caught between rising inflation pressure from the oil shock and a weak currency on one side, and soft domestic demand on the other. The Nikkei still added 2.1%.

In China, accelerated fiscal spending and a reaffirmed “moderately loose” policy stance from the PBoC supported the Shanghai Composite’s 2.8% gain, with Beijing’s chip self-sufficiency drive gaining traction. Domestic manufacturers are now expected to supply 46% of Chinese firms’ AI accelerator budgets over the next year, up from 30% currently.

Gold had a standout week, up 7.43% to $4,341.52/oz and briefly topping $4,350 on Friday, a two-month high, as falling energy prices and softening labour data reinforced the lower-for-longer rate narrative. Brent, meanwhile, fell over 8% for the week on hopes of a US-Iran deal to keep the Strait of Hormuz open.

Looking ahead: Strait of Hormuz negotiations remain the key swing factor for energy prices and the broader rate outlook. US CPI data lands this week with the Fed and markets still split on the September decision, and AI-trade volatility bears watching after last week’s chip-driven bounce.

Market Moves of the Week:

South African assets had a strong week on the back of encouraging policy signals from National Treasury, which noted that domestic bond spreads have tightened to levels now comparable with investment-grade emerging-market peers. Treasury also outlined plans for a principles-based fiscal rule, a structural shift worth watching for its longer-term implications for fiscal credibility and sovereign risk pricing. Separately, government confirmed plans to list its first US$500 million credit-guarantee vehicle, aimed at drawing private capital into infrastructure, with electricity transmission flagged as a priority area.

Domestic data was more mixed. The S&P Global South Africa PMI eased slightly to 50.3 in July from 50.5, holding just above the expansion threshold, while new vehicle sales rose a healthy 11.9% year-on-year, a reasonable proxy for consumer resilience given the interest rate environment.

Markets responded positively across the board. The 10-year government bond yield fell 27 basis points to 8.47%, and the rand strengthened 2.51% to R16.13 against the US dollar. The JSE All Share Index gained a strong 5.40% on the week, led by resources with the Resource 10 Index surging 16.86%. Financials and industrials also advanced, up 1.59% and 1.14% respectively, while listed property was the lone laggard, down 0.30%.

Chart of the Week:

As always, we appreciate your support and value your trust in LNKD Investment Managers.

Important Information

The information included above as well as individual companies and/or securities mentioned should not be construed as investment advice, a recommendation to buy or sell or an indication of trading intent on behalf of any LNKD Investment Managers product. This material is provided for informational purposes only and is not intended to be investment advice or a recommendation to take any particular investment action. Information contained herein is based upon sources we consider to be reliable; we do not, however, guarantee its accuracy. All charts and tables are shown for illustrative purposes only.

LNKD Investment Managers is an authorised financial services provider (FSP 51257).

Weekly Insights: Central Banks Hold Amid Rising Uncertainty

The Federal Reserve left its benchmark interest rate unchanged at 3.50%–3.75% for a fifth consecutive meeting, a decision widely expected by markets. While nine members of the Federal Open Market Committee voted to keep rates unchanged, three favoured a further increase, highlighting continued concerns over inflation.

The Federal Reserve’s preferred inflation measure provided some relief, with the Bureau of Economic Analysis (BEA) reporting that the core Personal Consumption Expenditures (PCE) price index, which excludes food and energy, rose 0.1% in June, down from 0.3% in May. Annual core inflation eased to 3.3% from 3.4%, while headline PCE inflation remained elevated at 3.7% despite a 0.1% monthly decline. The BEA also reported that the US economy expanded at an annualised rate of 1.5% in the second quarter, below consensus expectations and down from 2.1% in the first quarter, reflecting weaker government spending and slower investment and export growth.

Eurozone GDP expanded 0.4% in the second quarter, exceeding market expectations. Growth was supported by AI-related investment and government spending, which helped offset the drag from the U.S.-Iran conflict and higher energy prices. Spain recorded the strongest growth among the region’s largest economies, with GDP expanding 0.7%. Annual inflation increased to 2.9% in July from 2.8% in June, in line with expectations, while services inflation rose to 3.3% and non-energy industrial goods inflation increased to 0.9% from 0.7%.

The Bank of England left Bank Rate unchanged at 3.75%. The Monetary Policy Committee voted 6–3 in favour of maintaining the policy rate, with three members preferring a 25 basis point increase. Policymakers cited persistent inflationary pressures and heightened uncertainty, warning that a renewed escalation of the conflict in the Middle East could prolong energy price volatility and increase upside risks to inflation.

The Bank of Japan (BoJ) left its policy rate unchanged at 1.00%, following June’s increase to its highest level since 1995. One policy board member favoured a 25 basis point increase to 1.25%. The BoJ indicated that underlying inflation is approaching its 2% target and reiterated that future policy adjustments will depend on developments in economic activity, inflation and financial conditions.

China’s manufacturing Purchasing Managers’ Index (PMI) unexpectedly fell to 49.2 in July from 50.3 in June, below market expectations and marking its first contraction since February. The decline reflected weaker domestic demand, weather-related production disruptions and slower export activity, while new orders fell to 48.5, their lowest level in more than three years.

Investor demand for China’s semiconductor sector remained strong, with memory-chip manufacturer ChangXin Memory Technologies (CXMT) surging 466% on its market debut following Asia’s largest IPO of 2026. However, the broader semiconductor sector weakened later in the week as concerns over elevated valuations and AI-related capital expenditure weighed on sentiment.

Global equity markets were mixed over the week, with investors navigating the Federal Reserve’s policy decision, ongoing geopolitical tensions in the Middle East and continued volatility in AI-related stocks. In the US, major indices closed higher, with the Nasdaq Composite (+1.59%), S&P 500 (+1.05%) and Dow Jones Industrial Average (+1.04%) advancing.

European equities also ended the week higher, with the pan-European STOXX Europe 50 Index rising 1.23% in local currency terms. Gains were supported by better-than-expected corporate earnings and a recovery in sentiment towards AI-related stocks later in the week, while Brent crude oil remaining below USD 100 per barrel provided an additional tailwind. The UK’s FTSE 100 Index also advanced 1.23%.

Asian equity markets delivered mixed performance over the week. Japan’s Nikkei 225 Index declined 0.47%. In China, the Shanghai Composite Index gained 0.47%. Mainland technology shares came under pressure as semiconductor and other AI-related stocks weakened, although sentiment improved later in the week following stronger-than-expected US technology earnings. Meanwhile, Hong Kong’s Hang Seng Index advanced 3.78%, supported by gains in large internet companies, including Tencent and Alibaba.

Brent crude oil declined 8.54% over the week to USD 89.86 per barrel. Despite the weekly decline, Brent remained more than 22% higher for July, marking its strongest monthly gain since March, as escalating tensions in the Middle East fuelled concerns over global oil supplies.

Market Moves of the Week:

Statistics South Africa reported that producer inflation slowed to 7.5% year-on-year in June from 7.8% in May, below market expectations of 7.9%. The softer-than-expected reading was largely driven by lower fuel and food prices, indicating some moderation in upstream price pressures despite elevated consumer inflation. Separately, National Treasury recorded a budget surplus of R80.13 billion in June, indicating that government revenue exceeded expenditure during the month.

South African equities advanced over the week, with the JSE All Share Index rising 1.92%. Gains were led by the industrial (+2.89%), financial (+2.93%) and listed property (+3.60%) sectors, while resource shares (-0.24%) underperformed amid softer commodity prices. The rand also strengthened against the US dollar, appreciating 1.67% to close the week at R16.54/USD.

Chart of the Week:

As always, we appreciate your support and value your trust in LNKD Investment Managers.

Important Information

The information included above as well as individual companies and/or securities mentioned should not be construed as investment advice, a recommendation to buy or sell or an indication of trading intent on behalf of any LNKD Investment Managers product. This material is provided for informational purposes only and is not intended to be investment advice or a recommendation to take any particular investment action. Information contained herein is based upon sources we consider to be reliable; we do not, however, guarantee its accuracy. All charts and tables are shown for illustrative purposes only.

LNKD Investment Managers is an authorised financial services provider (FSP 51257).