

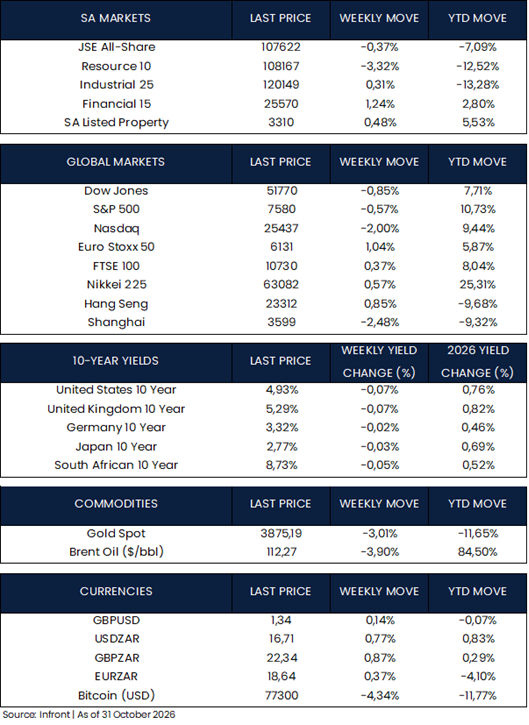
It was a week of two halves on Wall Street. Technology and artificial intelligence (AI) shares rallied early on upbeat earnings, new funding announcements and generally confident comments from company management. Then results from several of the largest tech companies, including Alphabet and Amazon, revived an old question: will the enormous sums being spent on AI earn an adequate return? By Friday, investors were moving out of the AI winners and into more defensive parts of the market.
Friday’s sell-off was severe. The tech-heavy Nasdaq fell 2.9%, its worst day since June, leaving it about 8% below its recent high. The S&P 500 lost 1.8% and the Dow Jones gave up 1.1%. Intel was the biggest casualty, falling almost 29% after it gave a weak outlook for the current quarter because of slowing PC demand. Amazon also slipped. Its third-quarter results fell short of expectations, it reported negative free cash flow of $42.4 billion, and it kept its plan to spend $220 billion on capital investment this year. Sentiment took a further knock from a Financial Times report that Blackstone had told investors Anthropic might not get an investment-grade credit rating after its market debut. Energy was a bright spot, with ExxonMobil and Chevron both rising after beating third-quarter forecasts.
October was a hard month for the AI trade: the Nasdaq fell 6.4%, its steepest monthly drop since March 2025. The S&P 500 slipped 1.8%, while the Dow, with its heavier weighting in traditional industries, gained 1.2%.
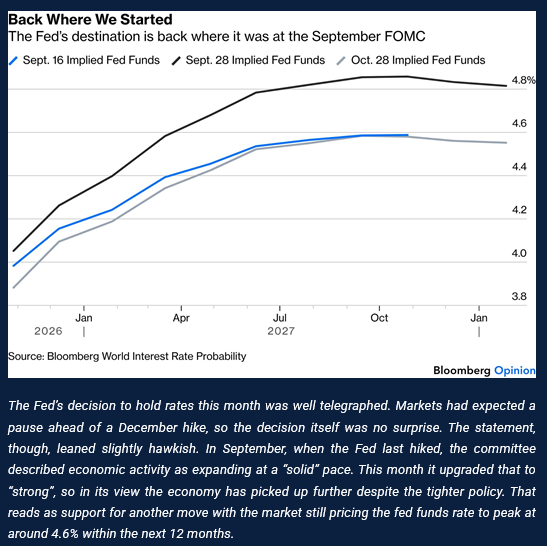
The US Federal Reserve kept interest rates on hold at 3.75% to 4.00%, as expected, after raising them by 0.25 percentage points in September. The tone, though, leaned towards further tightening. The Fed upgraded its view of the economy from growing at a “solid” pace to a “strong” one and noted that inflation remains elevated. Two of the twelve voting members, Cleveland Fed President Beth Hammack and Governor Lisa Cook, wanted another hike. Fed Chair Kevin Warsh pointed to strong productivity and business investment, restated the Fed’s commitment to its 2% inflation target and said recent tightening in financial conditions showed policy was starting to work. He declined to signal what the Fed would do in December. He also announced changes to the meeting calendar: the Fed will still meet eight times a year, but from 2027 fewer of those meetings will include a rate decision, with some given over to broader policy strategy. The week’s data supported the Fed’s upbeat view. US economic growth accelerated to an annualised 3.4% in the third quarter, from 2.2% in the second and ahead of forecasts of about 3%, helped by business investment and consumer spending.
In Europe, the European Central Bank also left rates unchanged, with its deposit rate at 2.5%. Policymakers said they had discussed a hike but decided unanimously to wait, citing tighter financial conditions while warning that the energy shock could push inflation higher. The bigger news was President Christine Lagarde’s announcement that she will step down on 7 February, nine months before her term ends, so that she can speak freely on politics, particularly developments in France. She is widely expected to take the helm of the World Economic Forum. The pan-European STOXX Europe 50 Index ended the week up 1.04%.
In the UK, Prime Minister Andy Burnham’s government presented its first Budget, and it brought few shocks. Chancellor John Healey raised taxes on banks, including a temporary doubling of the bank surcharge to 6%, and on gambling companies to pay for modest spending increases. He kept the target of a current budget surplus by 2029–30. Markets were relieved: the feared sell-off in government bonds did not happen, and 10-year yields edged lower. Burnham also ruled out a snap election in the next 12 months. The FTSE 100 gained 0.37%.
In Asia, Japan’s Nikkei 225 rose 0.57%, though it was caught up in Friday’s AI-driven selling. In China, a deepening sell-off in technology shares pulled the Shanghai Composite down 2.48%, while Hong Kong’s Hang Seng rallied late in the week to finish 0.85% higher.
The week’s most dramatic move came from Brazil. President Lula da Silva’s unexpected re-election over Flávio Bolsonaro, whom investors had expected to win, prompted a rapid unwinding of bets on a more fiscally conservative government. The Ibovespa plunged nearly 14% on Monday, triggering a temporary trading halt, and the real fell about 8% against the US dollar.
Oil remains a major concern. Brent crude rose above $113 a barrel on Friday, close to the four-year high of $116.72 reached on 23 October. The rise came on reports that President Trump had been briefed on options for renewed strikes against Iran, two separate tanker incidents in the Strait of Hormuz and a Ukrainian strike on a Russian refinery. Brent gained over 10% in October, an unwelcome development for inflation and for central banks trying to contain it.
Next week brings the US midterm elections on 3 November. All 435 House seats and 35 of the 100 Senate seats are up for election. Democrats are widely expected to win the House, while the Senate is more open, and a divided Congress would make it harder for President Trump to push through his agenda. The OPEC meeting, the US jobs report and a range of central bank decisions, including those of the Bank of England and the Reserve Bank of Australia, will also be watched closely, along with events in the Middle East and Ukraine.
Market Moves of the Week:
The most important local news this week was the size of the South African economy. On Thursday, Statistics South Africa published a routine recalculation, generally done about every five years, which found the economy is over 5% larger than previously thought. Nominal GDP for 2025 is now put at about R8.04 trillion, against the earlier estimate of R7.64 trillion. That widens South Africa’s lead over Nigeria as sub-Saharan Africa’s largest economy. Two changes drove the revision. The base year for the calculations moved from 2015 to 2022 to better reflect how the economy is now structured. The exercise also captured activity that previously went unmeasured, such as households and businesses generating their own electricity, e-hailing services, street hawkers, shebeens, informal recycling and some illegal activity. All ten sectors tracked showed higher output. Mining saw the largest increase, mainly because illegal mining is now measured better, having spread as the gold price soared. Finance, real estate and business services came next, followed by trade.
The economy has not changed overnight, but this matters because so many of the government’s key fiscal measures are expressed as a share of GDP. A larger economy makes the same amount of debt look more manageable. Credit rating agencies, including Moody’s, have said a better debt position is something they will watch when weighing further upgrades. South Africa’s rating has been moving in the right direction but is still below investment grade, so the revision is welcome support for that recovery.
The week’s other data were less encouraging. Producer inflation, which measures the prices businesses pay and receive and often feeds through to consumer prices over time, rose to 6.2% year-on-year in September from 5.0% in August.
The rand had a softer week and ended at around R16.71 to the US dollar. It weakened after the US Federal Reserve kept rates on hold with a hawkish tone, which weighed on gold and platinum, two of South Africa’s most important exports. The rand tends to follow US interest rate expectations as closely as local news. Investors were also waiting for domestic budget and trade data, watching a key US trade review of AGOA and looking ahead to next week’s local government elections. On the JSE, the All Share Index fell 0.37% over the week, held back by resource shares as gold stayed below the psychologically significant US$4,000 level. Government bonds held up better, with the South African 10-year government bond yield firming slightly and its yield easing to about 8.73%.
Chart of the Week:
As always, we appreciate your support and value your trust in LNKD Investment Managers.
The information included above as well as individual companies and/or securities mentioned should not be construed as investment advice, a recommendation to buy or sell or an indication of trading intent on behalf of any LNKD Investment Managers product. This material is provided for informational purposes only and is not intended to be investment advice or a recommendation to take any particular investment action. Information contained herein is based upon sources we consider to be reliable; we do not, however, guarantee its accuracy. All charts and tables are shown for illustrative purposes only.
LNKD Investment Managers is an authorised financial services provider (FSP 51257).