Weekly Insights: Bonds Under Pressure as Rates Rise

Global equity markets ended a turbulent week on a positive note, with US shares rallying on Friday despite a sharp rise in government bond yields that unsettled investors earlier in the week. The Dow Jones finished the week 0.3% higher, while the broader S&P 500 gained 1.2% and the technology-heavy Nasdaq rose 2%. Sentiment was also helped by a pullback in oil prices, with Brent crude falling 2.1% to $104.32 a barrel on renewed hopes that the Strait of Hormuz, one of the world’s most important shipping routes for oil, could reopen.

That optimism followed a proposal from Iran asking the US to return to the interim agreement reached in mid-June, which had produced a short-lived ceasefire before collapsing a few weeks later. Iran’s foreign minister offered to reopen the strait and resume nuclear talks within seven days, provided the US lifts its naval blockade, releases frozen Iranian assets and agrees to end the conflict on all fronts. Encouragingly, oil flows through Hormuz held steady at around 33.7 million barrels this week. Even so, oil markets remain highly sensitive to headlines, swinging between hopes for peace, signs of recovering Middle East energy supplies and speculation that the US may restrict diesel exports.

The US economy itself continues to show surprising strength. S&P Global’s September survey of business activity showed the economy expanding for a fourth consecutive month, with the composite index climbing to 58.4, its highest level in more than five years (any reading above 50 signals growth). Services led the way, rising to 58.7 from 56.5, while manufacturing also picked up meaningfully, rising to 57.0 from 53.9.

This strength, however, is a double-edged sword. Bond markets reacted sharply, with the yield on the 10-year US Treasury rising to its highest level since 2007 and the 30-year yield reaching levels last seen in 2004, closing the week at around 5.16% and 5.49% respectively. Rising yields reflect growing concern that inflation will stay stubbornly high, fuelled by elevated energy prices, a robust economy and hawkish comments from Federal Reserve Governor Michael Barr. Markets are now pricing in a roughly 64% chance that the Fed will raise interest rates in October, a notable shift from the rate-cutting expectations that dominated earlier in the year. For investors, higher yields matter because they raise borrowing costs across the economy and increase competition for equities from lower-risk assets.

American households are feeling the pressure. The University of Michigan’s consumer sentiment index fell 7% in September to 48.1, though this was marginally better than expected. More concerning was the jump in near-term inflation expectations, with consumers now anticipating inflation of 4.6% over the next year, the highest reading since June.

On the diplomatic front, Chinese President Xi Jinping concluded his first formal visit to Washington in 11 years. While the three-day state visit was rich in ceremony, from a state dinner to a promised pair of pandas for Atlanta, it produced little of substance. There were no major purchase commitments and no progress on artificial intelligence risks or the war in Iran. The one concrete outcome was an agreement to extend the existing US–China trade truce until 10 January, which removes a near-term source of uncertainty for markets.

In Europe, the STOXX Europe 50 rose more than 1% over the week as investors weighed improving economic growth and enthusiasm around artificial intelligence against concerns that high energy prices could prompt the European Central Bank to raise rates further. Eurozone business activity came in well ahead of expectations, with the composite index rising to 53.1 from 52.0. Germany strengthened, and France returned to growth for the first time in ten months. The picture in the UK was more subdued. Retail sales weakened further and orders placed with suppliers fell at the fastest rate since records began in 1983, while overall business activity slowed as the services sector lost momentum. The FTSE 100 nonetheless edged 0.3% higher.

In Asia, Japanese markets traded for only two days due to public holidays, but made up for lost time with the Nikkei 225 rising 1.8% as AI and semiconductor shares caught up with the earlier gains in US technology stocks. Chinese markets were softer, with the Shanghai Composite down 0.6% ahead of Friday’s Mid-Autumn Festival holiday and Hong Kong’s Hang Seng Index falling 1.0%, weighed down by technology stocks.

Looking ahead, developments between the US, Iran and Gulf states will remain firmly in focus, as energy prices and resilient economic data continue to push global bond yields to multi-decade highs. In the US, attention turns to the September jobs report, alongside key inflation data in the form of the PCE price index, as well as personal income and spending figures and the ISM business surveys. In Europe, inflation and unemployment figures will be closely watched, with markets already anticipating several rate hikes from the ECB, while China releases its latest business activity data in a holiday-shortened week.

Market Moves of the Week:

The South African Reserve Bank (SARB) raised interest rates for the second time this year on Wednesday, lifting the repo rate by 25 basis points to 7.25%. The decision was widely anticipated and the Monetary Policy Committee voted unanimously in favour. For households and businesses, this takes the prime lending rate to 10.75%, meaning slightly higher repayments on home loans, vehicle finance and other variable-rate debt.

Governor Lesetja Kganyago explained that the war in Iran has triggered large and sustained price shocks, and that tighter policy is needed to stop higher inflation from becoming entrenched in the economy. While he acknowledged that the global economy had absorbed some of this year’s energy shocks reasonably well, he cautioned that vulnerabilities are building, with renewed fuel-price pressure the most immediate concern for South Africa.

The hike comes at a difficult moment for the local economy, which contracted by 0.2% in the second quarter. The SARB nonetheless expects activity to recover in the second half of the year, forecasting growth of 1.2% for 2026 and around 2% over the medium term, though the Governor noted that the risks to this outlook remain tilted to the downside. The next and final rate decision of the year is scheduled for Thursday, 19 November.

Earlier on Wednesday, Statistics South Africa reported that consumer inflation edged up to 4.4% in August from 4.3% in July. This was slightly better than the 4.5% economists had expected, and core inflation, which strips out volatile food and fuel prices, eased to 4.1% from 4.2%. Prices were also flat month-on-month on both measures. However, food inflation ticked higher for the first time since November 2025, rising to 1.1% from 0.9%. Importantly, headline inflation now sits 1.4 percentage points above the SARB’s new 3% inflation target, which helps explain the Bank’s willingness to act even as growth remains fragile.

Local markets had a softer week. The FTSE/JSE All Share Index fell 1.9%, dragged lower by a 4% decline in resource shares, while the rand weakened to R16,27 against the US dollar. Local bonds also came under pressure, with the yield on the South African 10-year government bond ending the week at 8.94%.

Chart of the Week:

As always, we appreciate your support and value your trust in LNKD Investment Solutions.

The information included above as well as individual companies and/or securities mentioned should not be construed as investment advice, a recommendation to buy or sell or an indication of trading intent on behalf of any LNKD Investment Managers product. This material is provided for informational purposes only and is not intended to be investment advice or a recommendation to take any particular investment action. Information contained herein is based upon sources we consider to be reliable; we do not, however, guarantee its accuracy. All charts and tables are shown for illustrative purposes only.

LNKD Investment Managers is an authorised financial services provider (FSP 51257).

Weekly Insights: Policy Tightens as Growth Holds Up

Global markets navigated another eventful week as investors balanced tighter monetary policy, elevated energy prices and mixed economic data. Central banks remained firmly in focus, with the Federal Reserve and the Bank of Japan raising rates, while the Bank of England remained on hold. Against this backdrop, equity markets were mixed, bond yields remained volatile and energy prices continued to influence the inflation outlook.

In the US, technology shares proved relatively resilient, helping the Nasdaq outperform, while smaller companies lagged. Sentiment towards AI-related stocks also improved as the week progressed, following an initially cautious reaction to renewed debate around the risks associated with advanced AI development.

The Federal Reserve raised the fed funds target range by 25 basis points to 3.75%–4.00%, its first increase in three years. With the move widely anticipated, attention shifted to the Fed’s updated projections, which showed a firmer inflation outlook and suggested that another increase remains possible before year-end. Stronger growth and employment assumptions also indicate that policymakers believe the economy can absorb somewhat tighter monetary conditions.

Economic data remained mixed but generally resilient. Retail sales rose strongly in August and initial jobless claims declined, while manufacturing surveys softened and housing activity remained under pressure. The US 10-year Treasury yield briefly moved above 5.0%, reflecting uncertainty around the future path of rates, while oil prices remained volatile amid renewed concerns over Middle East supply disruptions.

In Europe, inflation remained the central theme. Eurozone consumer inflation accelerated to 3.2% year on year in August, largely reflecting higher energy costs, while core inflation remained more contained at 2.4%. Industrial activity stayed weak and economic sentiment softened, with the ZEW expectations index declining in September, reinforcing concerns around the strength of the region’s recovery.

In the UK, the Bank of England kept its policy rate unchanged at 3.75%, although the 6–3 vote highlighted continued concern around inflation. UK inflation rose to 3.1% in August, while unemployment remained steady at 4.9%. With price pressures still above target but economic activity relatively subdued, policymakers continue to face a difficult balance between containing inflation and avoiding unnecessary weakness in growth.

Japanese equities ended the week higher, supported by a recovery in technology shares and a weaker yen, which provided a tailwind for exporters. The Bank of Japan raised its policy rate by 25 basis points to 1.25%, its highest level in more than three decades. While the move was expected, the split vote and limited guidance on the pace of future increases suggested that further tightening may proceed cautiously.

Chinese markets were more mixed, with mainland equities proving more resilient than Hong Kong. Technology shares recovered towards the end of the week, led by semiconductor and AI-related companies. Economic data continued to highlight an uneven recovery, with industrial production accelerating to 5.2% year on year in August, while retail sales growth remained subdued at just 0.4%. Weak investment, ongoing property-sector pressure and softer credit growth continue to weigh on domestic demand.

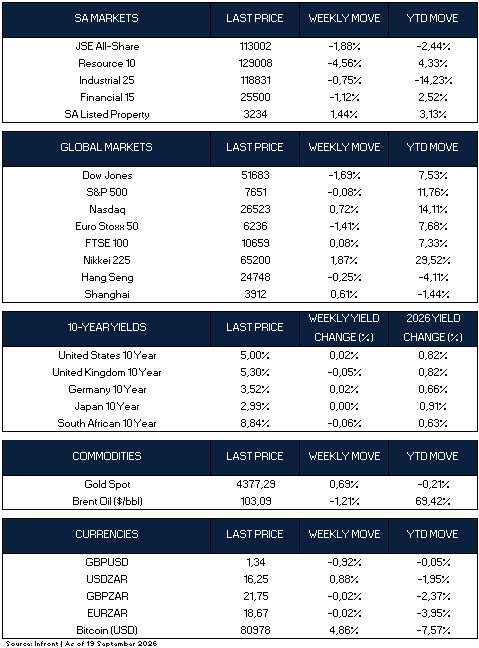
Overall, global markets delivered a mixed performance. The S&P 500 edged 0.08% lower, while the Nasdaq gained 0.72% and the Dow Jones declined 1.69%. The Euro Stoxx 50 fell 1.41%, while the FTSE 100 was broadly unchanged. Asian markets were stronger overall, led by Japan’s Nikkei 225, which gained 1.87%. Brent crude oil fell 1.21% for the week but remains 69.42% higher year to date, while gold gained 0.69% and Bitcoin rose 4.86%.

Market Moves of the Week:

Turning to South Africa, the latest data painted a mixed picture. Manufacturing conditions remained under pressure, with the Absa/BER Manufacturing Confidence Index declining to 27 from 31 and remaining below its long-term average. Around 70% of manufacturers continued to describe business conditions as unsatisfactory, with weak domestic sales and export orders weighing on sentiment.

The consumer backdrop was more encouraging. Real retail sales increased 3.4% year on year in July, ahead of expectations; and up from a revised 1.1% in June. Consumer confidence also improved, with the FNB/BER Consumer Confidence Index rising to -13 from -19. While households continue to face pressure from elevated fuel and borrowing costs, the data suggest that consumer spending is holding up better than activity in parts of the industrial economy.

Inflation expectations also remained relatively well contained. Expectations for 2026 were unchanged at 4.4%, while expectations for 2027 eased to 4.0%. Household inflation expectations declined more noticeably, an encouraging development for the South African Reserve Bank as it assesses the potential impact of higher oil prices and external cost pressures.

Against this backdrop, South African markets had a difficult week. The JSE All Share Index fell 1.88%, led by a 4.56% decline in resource shares, while industrials and financials declined 0.75% and 1.12% respectively. Listed property provided a relative bright spot, gaining 1.44%. The rand weakened against the US dollar, which closed the week at R16.25, while the South African 10-year government bond yield declined to 8.84%.

Chart of the Week:

As always, we appreciate your support and value your trust in LNKD Investment Managers.

The information included above as well as individual companies and/or securities mentioned should not be construed as investment advice, a recommendation to buy or sell or an indication of trading intent on behalf of any LNKD Investment Managers product. This material is provided for informational purposes only and is not intended to be investment advice or a recommendation to take any particular investment action. Information contained herein is based upon sources we consider to be reliable; we do not, however, guarantee its accuracy. All charts and tables are shown for illustrative purposes only.

LNKD Investment Managers is an authorised financial services provider (FSP 51257).
Weekly Insights: Global Bond Yields Reach Fresh 2026 Highs

Global equities ended the week lower amid renewed US-Iran conflict, with Brent crude climbing to $104.35 per barrel. The International Energy Agency pushed back its forecast for a full recovery in Middle Eastern oil supplies to 2027, while projecting global oil demand to decline by 2.5 million barrels per day in 2026.

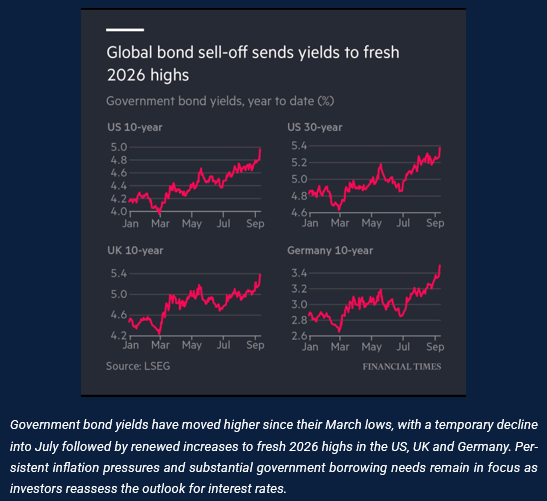
Government bonds came under pressure across global markets, with yields reaching fresh 2026 highs in the US, UK and Germany. Higher energy prices reinforced expectations of further interest rate increases, while concerns over fiscal deficits and heavy debt issuance added to the selling pressure. Corporate borrowing also contributed to debt supply, with large US cloud providers raising around USD 220 billion over the past year to fund cloud and data centre expansion.

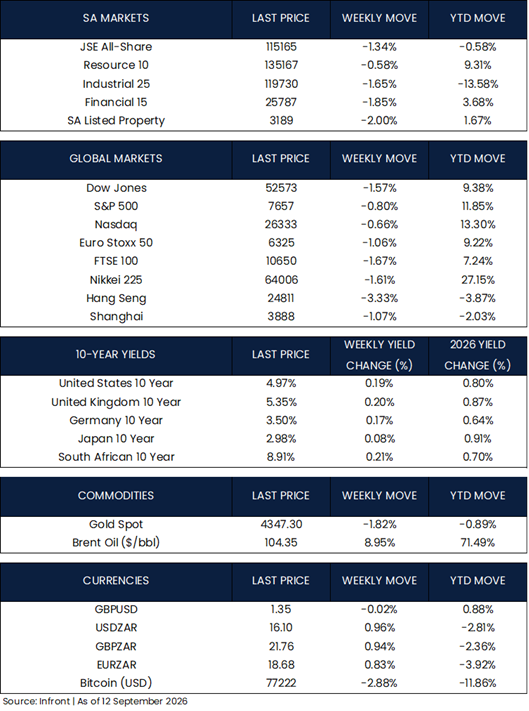
In the US, the 10-year Treasury yield increased 19 basis points over the week to 4.97%. The Treasury also announced plans to improve liquidity in longer dated bonds through a buyback of up to USD 6 billion in debt maturing in 10 to 20 years, triple the size of its previous long dated operation.

US inflation data released this week showed consumer prices increasing 0.4% in August, up from 0.1% in July. Annual headline inflation remained at 3.4%, while core inflation eased to 2.4% from 2.5%. Producer prices also increased 0.4% over the month, taking annual producer inflation to 5.4%.

Other data released during the week showed new applications for unemployment benefits falling by 1,000 to 206,000 in the week ended 5 September. Housing activity was softer, with existing home sales declining 2.0% in August to an annualised rate of 3.98 million, their slowest pace in more than a year.

Against this backdrop, US equities closed the week lower, with the Dow declining 1.57%, the S&P 500 falling 0.80% and the Nasdaq losing 0.66%.

European equities also declined, with the Euro Stoxx 50 down 1.06% and the FTSE 100 losing 1.67%. The ECB announced a 25 basis point increase in its deposit rate to 2.50%, effective 16 September, as higher energy costs fuelled inflation. In France, the government lowered its 2026 growth forecast to 0.5% from 0.7%, while also confirming it would miss its budget deficit target.

UK growth data released during the week showed the economy expanding 0.4% in July, ahead of expectations of no growth. Services provided the largest contribution, with production and construction also increasing.

Government bond yields continued rising across the region, with Germany’s 10-year yield increasing 17 basis points to 3.50% and the UK equivalent climbing 20 basis points to 5.35%.

In Japan, producer prices fell 0.2%, marking their first monthly decline in a year as energy and agricultural prices eased. Annual producer inflation also eased to 7.6% from 7.7%, while import prices fell 3.0% over the month, partly reflecting a stronger yen and lower petroleum and gas prices during August.

Manufacturing confidence reached its highest level since December 2021, supported by strong semiconductor and data centre demand, with transport companies also benefiting from this activity.

Japanese equities ended the week lower, with the Nikkei 225 declining 1.61%, while the 10-year government bond yield increased 8 basis points to 2.98%.

Chinese trade data released this week showed exports increasing 25% year-on-year in August, up from 23.9% in July, while imports grew 28.2%. The trade surplus reached USD 119.1 billion, with technology related exports continuing to expand.

On inflation, data showed annual producer price growth accelerating to 3.8% from 3.5%, above expectations of 3.6%, while consumer prices increased 0.8% year-on-year.

Chinese equities ended the week lower, with the Shanghai Composite declining 1.07% and Hong Kong’s Hang Seng losing 3.33%.

In the week ahead, interest rates will remain in focus as the Federal Reserve, Bank of England and Bank of Japan announce their monetary policy decisions against a backdrop of elevated energy prices. The Bank of England will also decide how much further to reduce its bond holdings over the coming year.

Market Moves of the Week:

Turning to South Africa, equities ended the week lower, with the JSE All-Share Index declining 1.34%. Listed property led the losses with a 2.00% decline, followed by financials and industrials, down 1.85% and 1.65% respectively, while resources recorded a smaller decline of 0.58%. Local government bonds also came under pressure, with the 10-year yield increasing 21 basis points over the week to 8.91%.

On the economy, data released this week showed GDP contracting 0.2% quarter on quarter in the second quarter after six consecutive quarters of growth, with mining, manufacturing and trade declining. Household consumption increased 0.4%, while fixed investment fell for a second consecutive quarter and higher imports also reduced growth.

Higher import spending also contributed to the current account shifting from a surplus of 2.3% of GDP in the first quarter to a deficit of 2.6% in the second. Oil costs were a major contributor, with the value of crude-oil imports increasing 82% while volumes rose just 1.8%. In the currency markets, the rand weakened against the major currencies, with the US dollar gaining 0.96% to R16.10, sterling rising 0.94% to R21.76 and the euro advancing 0.83% to R18.68 over the week. 

Chart of the Week:

As always, we appreciate your support and value your trust in LNKD Investment Managers.

The information included above as well as individual companies and/or securities mentioned should not be construed as investment advice, a recommendation to buy or sell or an indication of trading intent on behalf of any LNKD Investment Managers product. This material is provided for informational purposes only and is not intended to be investment advice or a recommendation to take any particular investment action. Information contained herein is based upon sources we consider to be reliable; we do not, however, guarantee its accuracy. All charts and tables are shown for illustrative purposes only.

LNKD Investment Managers is an authorised financial services provider (FSP 51257).
Weekly Insights: US Payrolls Rebound Sharply

US employment data surprised to the upside in August, with nonfarm payrolls rising by 162,000, well ahead of expectations, while upward revisions to June and July added a further 55,000 jobs. The unemployment rate held steady at 4.1%, while the labour force participation rate increased to 61.6%. Other labour market indicators during the week were somewhat mixed, with job openings edging higher to 7.27 million but falling short of expectations, while initial jobless claims were little changed. ADP data showed that private employers added just 38,000 jobs in August, the lowest monthly increase since January.

US business activity continued to point to economic expansion in August. Despite easing from 55.6 in July to 54.6, the ISM manufacturing PMI remained in expansion territory for an eighth consecutive month, with new orders, production and employment all continuing to expand. Meanwhile, services activity strengthened, with the ISM services PMI rising 1.3 percentage points to 55.4 as new orders and backlogs improved, although the prices paid component climbed to its highest level in four years.

The conflict between Washington and Tehran escalated sharply this week, with the US launching a pre-emptive strike against an Iranian island in the Strait of Hormuz to prevent Iran from laying new sea mines. Brent crude rose 8.64% over the week to $95.78/bbl as concerns over potential supply disruptions resurfaced, adding to inflation concerns.

Global government bond yields also rose sharply, reaching levels not seen in years. The US 10-year Treasury yield reached an intraday high of 4.85%, its highest since January 2025, while yields in the UK and Japan also rose to multi-year highs. A Bloomberg gauge of global sovereign bonds climbed to 3.78%, its highest level since mid-2008. Yields subsequently retraced from their intraday highs, with the US 10-year Treasury closing the week at 4.79%, up 7 bps.

Major US equity indices finished the week narrowly mixed as investors weighed renewed US-Iran hostilities, higher oil prices, stronger employment data and shifting expectations for Federal Reserve policy. The Dow Jones Industrial Average fell 0.27%, while the S&P 500 gained 0.09% and the Nasdaq Composite rose 0.40%.

Eurozone retail sales fell 0.6% month on month in July, the sharpest decline since May 2025, with Germany, Spain and Italy all recording lower sales volumes, while France and the Netherlands saw growth. Producer price inflation, however, surprised to the upside, with prices rising 1.6% from June, driven by a sharp increase in energy-related costs. Capital goods prices rose by just 0.3%, while prices for nondurable consumer goods declined.

European equities came under pressure early in the week as renewed US-Iran hostilities pushed energy prices and government bond yields higher. Sentiment later stabilised as energy prices eased from their highs and rate concerns moderated. The STOXX Europe 50 fell 1.43% for the week, while the FTSE 100 was broadly flat.

China’s economic data remained mixed in August, with the official manufacturing PMI improving to 49.8 from 49.2, although it stayed below the 50 threshold for a second consecutive month. Production, new orders and export orders improved, but the official non-manufacturing PMI remained at 49.0, its lowest level since December 2022. The private sector painted a more positive picture, with the RatingDog manufacturing PMI rising to 51.5 from 50.9, supported by stronger output and new orders, while the services PMI increased to 51.4 on stronger domestic demand.

Asian markets were mixed over the week. Japan’s Nikkei 225 fell 2.02%, pressured by rising JGB yields and growing expectations of near-term BoJ tightening, while a stronger yen later in the week added further pressure on exporters.

Mainland Chinese equities diverged from Hong Kong, with fading momentum in AI-related shares weighing on the Shanghai Composite, which fell 0.56%, while the Hang Seng rose 0.32% in local currency terms as it recovered towards the end of the week.

Market Moves of the Week:

South Africa’s manufacturing sector weakened further in August, with the Absa Manufacturing PMI falling to 45.8 from 46.8, marking its fourth consecutive monthly decline and its lowest reading of 2026. The deterioration was driven by a sharp drop in business activity and new orders, with Absa pointing to subdued domestic demand, weak consumer confidence, and softer spending on non-essential goods. Export sales, however, showed some improvement.

The broader private sector offered a slightly more positive signal, with the S&P Global PMI edging up to 50.5 from 50.3, supported by a modest increase in new orders and a second consecutive month of output growth. Purchasing activity also strengthened, although export sales remained only marginally positive, suggesting that the path to a stronger recovery remains uncertain.

South African equities came under pressure this week, with the JSE All Share falling 1.22%, led by a 2.30% decline in the Resources 10 and a 1.44% fall in the Industrial 25. Listed property and Financials were relatively resilient, slipping 0.14% and gaining 0.23%, respectively. The rand, however, strengthened against the US dollar, closing Friday at R15.95/$.

Chart of the Week:

As always, we appreciate your support and value your trust in LNDK Investment Managers.

The information included above as well as individual companies and/or securities mentioned should not be construed as investment advice, a recommendation to buy or sell or an indication of trading intent on behalf of any LNKD Investment Managers product. This material is provided for informational purposes only and is not intended to be investment advice or a recommendation to take any particular investment action. Information contained herein is based upon sources we consider to be reliable; we do not, however, guarantee its accuracy. All charts and tables are shown for illustrative purposes only.

LNKD Investment Managers is an authorised financial services provider (FSP 51257).